Key Takeaways
- Coastal buyers should evaluate flood exposure, insurance availability, property condition, and local restrictions before making an offer.
- The true cost of a Crystal Coast home includes more than the loan payment. Plan for insurance, association fees, maintenance, utilities, and storm preparation.
- North Carolina’s due diligence period is valuable time for inspections, document review, insurance quotes, and financing confirmation.
- Oceanfront, soundfront, mainland, and condominium properties can offer very different lifestyles, risks, and long-term responsibilities.
Buying on North Carolina’s Crystal Coast is about more than finding a home with water views. The right property should fit the way you expect to use it, whether that means a full-time residence near Morehead City, a beach retreat in Atlantic Beach or Emerald Isle, a boating-focused home near Beaufort, or a quieter place around Harkers Island. Buyers who want a neighborhood-level perspective can work with Morehead City, NC, real estate agent Linda Rike. Linda Rike Real Estate is a coastal brokerage whose website offers home search, buying, and selling, as well as neighborhood information for Morehead City, Beaufort, Atlantic Beach, Emerald Isle, Harkers Island, Swansboro, and surrounding Carteret County communities. That local focus can be especially useful when comparing waterfront access, property types, and the ownership questions that do not show up in listing photos.
Define Your Coastal Lifestyle
Start with the purpose of the purchase. A primary home may require convenient access to groceries, medical care, schools, and year-round services. A second home may place more value on low-maintenance features and lock-and-leave convenience. A vacation rental requires a close look at local and association rental rules, furnishing costs, management needs, and periods when the home may be vacant. Also, decide what “waterfront” means to you. Oceanfront living, soundside views, deep-water access, marina proximity, and a home a short drive from the beach are not interchangeable. Each can affect exposure, maintenance, privacy, travel time, and resale appeal.
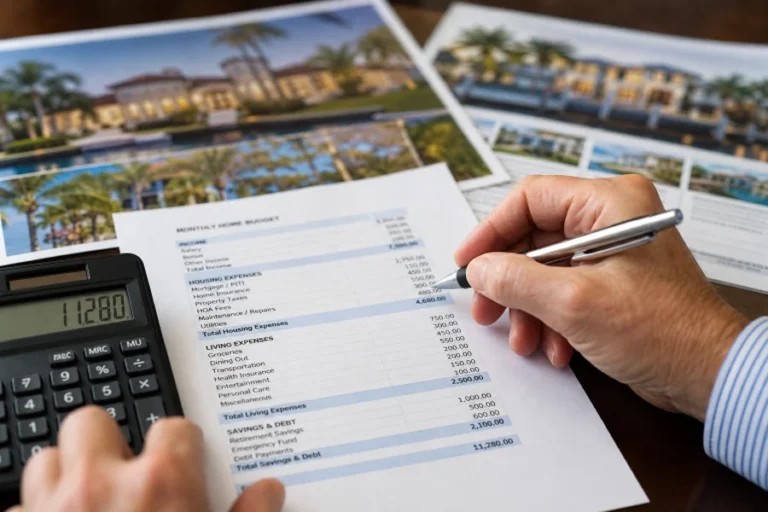
Build a Complete Coastal Home Budget
A lower purchase price does not always produce a lower cost of ownership. Before touring seriously, estimate both monthly and annual expenses, including:
- Mortgage principal, interest, taxes, and homeowners’ insurance.
- Wind, hail, and flood coverage when applicable.
- HOA or condominium dues, plus possible special assessments.
- Utilities, lawn care, pest control, and property management.
- Maintenance for roofs, exterior siding, decks, HVAC equipment, and drainage.
For example, a home that is less expensive upfront may carry higher annual costs if it has an older roof, exposed decks, aging mechanical systems, or insurance premiums that differ from a comparable inland property. Ask for estimates before deciding that a home fits your budget.
Compare Crystal Coast Communities
Compare communities according to daily life, not only beach distance. Mainland areas may offer easier access to services and a broader mix of home styles. Beach communities can provide immediate access to the shore but may bring seasonal traffic, stronger salt-air exposure, and more vacation-rental activity. Soundside and harbor locations may appeal to boaters, but buyers should understand water depth, access, shoreline condition, and dock potential.
- Morehead City: Consider access to shops, restaurants, medical services, marinas, and employment centers.
- Beaufort: Look at historic character, lot configuration, renovation needs, and proximity to waterfront amenities.
- Atlantic Beach and Emerald Isle: Evaluate beach access, rental activity, traffic patterns, and exterior maintenance demands.
- Harkers Island and nearby waterfront areas: Review boating lifestyle, road access, flood conditions, and practical service needs.
Check Flood Risk and Insurance Early
Do not wait until the final days of due diligence to investigate flood exposure and insurance. Use the exact property address to review mapping, ask whether an elevation certificate is available, and request quotes from qualified insurance professionals. FEMA’s Map Service Center can help buyers locate current flood map information for a specific area, but maps are only one part of the property review. Ask about prior flooding, storm damage, drainage issues, deductibles, coverage limits, and claims history when available. Standard homeowners’ policies generally do not cover flood damage, so buyers should discuss the appropriate coverage with an insurance professional rather than making assumptions.
Use a Coastal Inspection Plan
A general home inspection is important, but coastal conditions may justify additional review. Depending on the property, consider a roof and attic evaluation, a crawl-space moisture assessment, a wood-destroying insect inspection, an HVAC and electrical assessment, septic or well testing, and a review of docks, bulkheads, seawalls, or shoreline structures. A waterfront view can be compelling, but an aging bulkhead or deteriorating deck may materially affect future costs. Inspections should help you identify the property’s condition, not simply confirm the features that attracted you to it.
Understand North Carolina Due Diligence
The due diligence period is the contractual window in which buyers investigate the home and decide whether to proceed. Read the agreement carefully, track every deadline, schedule inspections promptly, confirm financing, obtain insurance quotes, and request surveys, permits, repair records, disclosures, and association documents. Buyers should also ask the closing attorney about title matters, easements, and recorded restrictions. This is general information, not legal, lending, insurance, or tax advice.
Review Waterfront Rules and Future Projects
If you hope to add a dock, repair a bulkhead, elevate a structure, improve drainage, or rebuild after storm damage, investigate those plans before closing. Local zoning, setbacks, association rules, shoreline conditions, and permit requirements may affect what can be done on a particular lot. North Carolina’s oceanfront rebuilding guidance explains that certain coastal projects can require CAMA permits.
Prepare a Reasoned Offer
A strong offer is not necessarily the highest offer. It is one supported by comparable sales, sound financing, realistic deadlines, and an understanding of repairs and insurance costs. Avoid giving up meaningful protections to compete. Coastal value can reflect views, water access, elevation, rental history, condition, and maintenance needs, so compare properties on the full ownership picture.
Plan for Long-Term Coastal Ownership
After closing, establish a maintenance and storm-readiness routine. Inspect the roof and exterior regularly, keep drainage paths clear, monitor crawl spaces, use appropriate corrosion-resistant hardware for repairs, document the home and belongings for insurance purposes, and maintain a reserve fund. A practical storm checklist for outdoor furniture, shutters, vehicles, and utilities can reduce the need for last-minute decisions when severe weather approaches.
Frequently Asked Questions
Is a Crystal Coast home a good investment?
It can provide lifestyle value, rental income potential, or long-term ownership appeal, but outcomes depend on the purchase price, financing, maintenance, insurance, occupancy, and local rules. Buyers should avoid treating any property as a guaranteed financial result.
Should I consider flood insurance if it is not required?
Discuss that question with an insurance professional. Flood exposure can exist outside the areas buyers expect, and the right coverage decision depends on the property, policy terms, and your risk tolerance.
What is the most common coastal buying mistake?
Falling in love with the view before reviewing the total cost of ownership. Insurance, elevation, drainage, roof condition, association documents, and shoreline improvements deserve careful attention before contractual deadlines expire.
Do condominium buyers need a separate checklist?
Yes. Review the association budget, reserves, master insurance, rental and pet rules, special assessments, storm responsibilities, and the division between unit maintenance and common-area maintenance.
Conclusion
Buying a home on North Carolina’s Crystal Coast can be deeply rewarding when the decision is based on more than location, views, or proximity to the beach alone. A successful purchase starts with defining the lifestyle you want and understanding how the property’s location, condition, insurance needs, maintenance requirements, and long-term costs fit into that plan. Calculate the full cost of ownership, investigate coastal risks and property condition early, review important documents carefully, respect contract deadlines, and plan for the practical realities of maintaining a home near the water. Taking time to compare properties and ask the right questions can help prevent costly surprises after closing. With thoughtful research and realistic expectations, buyers can make a more confident decision and enjoy the Crystal Coast lifestyle while keeping their homeownership experience manageable for years to come.